Asset Finance
Helping you get the equipment your business needs, without tying up your cash.
If you run a business, the right machines, vehicles or tools can help you take on more work. Paying for them in one go is not always practical. Asset finance lets you spread the cost of equipment or vehicles over an agreed term, while you use them in the business.
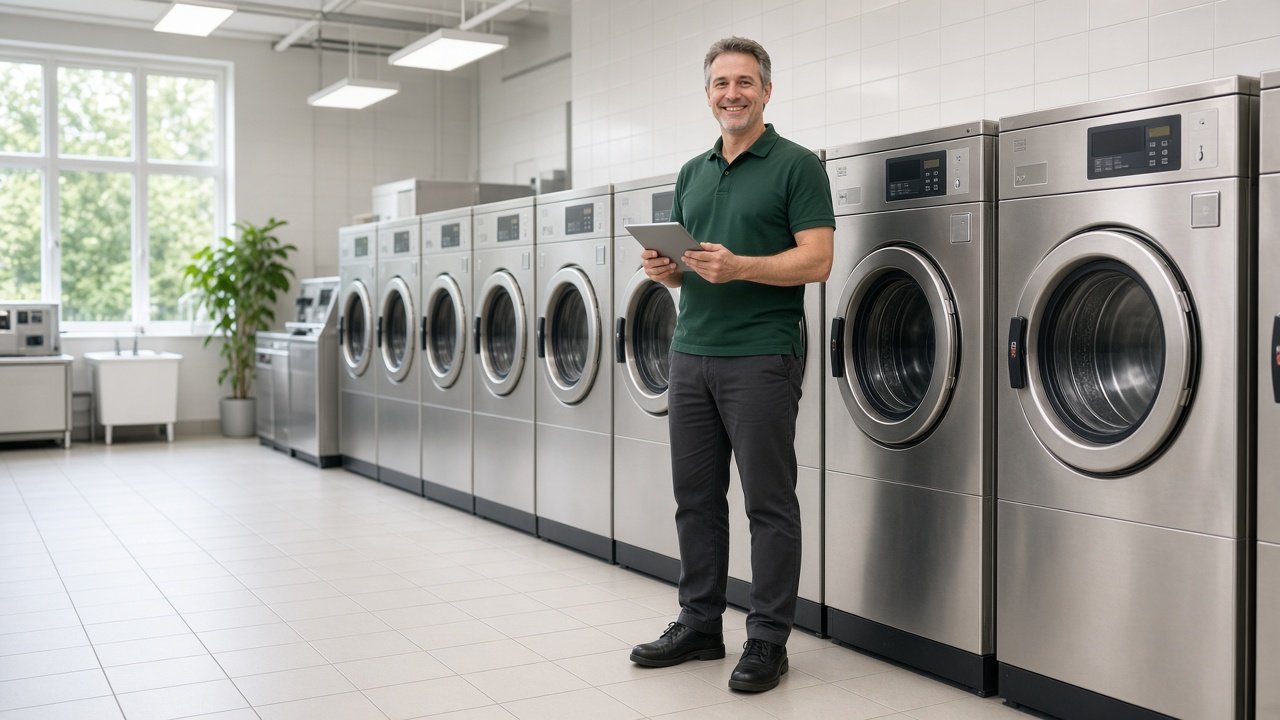
SM Finance works with UK business owners who need finance for equipment and vehicles. That includes laundries and launderettes, cafes, salons, trades and transport firms, as well as other established small and medium-sized businesses.
We will take the time to understand what you want to buy, how your business trades, and which type of agreement may suit you. We then introduce you to a panel of finance providers. We do not lend the money ourselves.
Finance is subject to status and is for business use only. Some business finance is not regulated by the Financial Conduct Authority. We may receive a commission from a finance provider if an agreement goes ahead. We will tell you about this.
Arrange a free appointment · Call 020 4511 9511 · WhatsApp 07863 083315
Why asset finance matters for your business
Most growing businesses reach a point where they need new equipment to take on more work. Paying for it all at once can drain the cash you need for wages, stock and rent. Asset finance helps you get the equipment now and pay for it over time.
What is asset finance?
Asset finance is a way of funding equipment, machinery or vehicles that your business will use. Instead of paying the full amount to the supplier up front, a finance provider pays for the asset and you repay them under a hire purchase or lease agreement, usually over a fixed term.
It is commonly used when a business wants to:
- buy new or used equipment without depleting cash reserves
- replace or upgrade machines that are coming to the end of their life
- add vehicles or tools as the business grows
- release capital from equipment the business already owns, where refinance or sale and leaseback is available
Asset finance is different from a commercial mortgage, which is secured on property, and from a general business loan, which is not tied to a specific piece of equipment. Those options are covered briefly below, and we can discuss them if they are a better fit.
The products we can introduce
The right agreement depends on the asset, how long you need it for, and whether you want to own it at the end. We will explain the differences in plain English before any introduction is made. Availability, terms and eligibility depend on the finance provider and on your circumstances.
Hire purchase
You hire the equipment or vehicle over an agreed term and, once the payments (and any final option-to-purchase payment) are made, you own it. This often suits businesses that want to keep the asset at the end.
Finance lease
You use the asset for the term of the lease and pay an agreed rental. At the end, there is usually an option to extend the lease, return the asset, or arrange a sale, depending on the agreement. You do not automatically own the asset.
Operating lease
You use the asset for a set period and return it at the end, much like a long-term rental. This can suit assets you may want to replace regularly, such as some vehicles. You would not normally own the asset.
Refinance, or sale and leaseback
If you already own equipment, it may be possible to refinance it, or to sell it to a finance provider and lease it back. This can release cash for other business use while you continue to use the same machines. It is not available in every case and depends on the age, condition and value of the asset, and on the provider.
Equipment and vehicle finance
This covers a wide range of business assets, for example:
- commercial laundry equipment — washers, dryers, ironers and related machinery
- cafe and restaurant equipment, such as ovens, coffee machines and refrigeration
- salon and clinic equipment
- tools, plant and machinery for trades
- vans, cars used for business, and other commercial vehicles
- shop fittings and other business equipment, where a provider will consider them
New and used equipment may be considered, depending on the supplier, the age of the asset and the provider’s criteria.
Business loans and commercial mortgages
Asset finance is not the only option for a business. If you need working capital, stock or funds that are not tied to a particular machine, a business loan may be more suitable. If you want to buy, refinance or raise capital against the premises you trade from — a shop, workshop, laundry or similar — a commercial or owner-occupier mortgage may be the better route.
We can talk you through these alongside asset finance. See also our pages on Small Business Loans, Commercial Loans and Owner-Occupier Mortgages.
Who it can help
We work with established UK businesses that need equipment or vehicles to trade and grow.
Other SMEs are welcome to enquire. If asset finance is not the right route, we will say so and, where we can, point you towards a more suitable type of business finance.
Why business owners use asset finance
- Keep cash in the business. You pay for the asset over time, rather than in a single lump sum.
- Match payments to use. The equipment can start earning for the business while you repay it.
- Plan your outgoings. Many agreements have a regular, agreed repayment, so you can budget with more certainty.
- New or replacement kit. You can upgrade worn machines, or add capacity, when the business needs it.
- A route to ownership, if you want it. Hire purchase is designed so that you can own the asset at the end of the term.
- Possible tax treatment. The tax position depends on the type of agreement and on your circumstances. This is not tax advice, and you should speak to your accountant about how any agreement would be treated for your business.
These are general features of asset finance. They are not a guarantee of a particular outcome, rate or saving, and not every feature applies to every type of agreement.
Eligibility and documents
Each finance provider has its own criteria. As a guide, providers usually want to see that the business is UK-based, is trading, and can afford the repayments. Limited companies are common applicants. Sole traders and partnerships may also be considered, though some of those agreements can fall under different regulatory rules, which we will explain.
To review a case we typically ask for:
- the supplier’s quote for the equipment or vehicles, including whether the items are new or used and the total cost
- the last 2 years’ accounts
- the last 3–6 months’ business bank statements
- directors’ or owners’ identity and address details, for credit and anti-money-laundering checks
- details of any deposit you can put in, and the term you have in mind
We may also need further information about the business, its owners and the asset. Sending a complete pack at the outset helps the provider assess the case more smoothly. An enquiry does not guarantee that finance will be offered.
How it works
Arrange a free appointment · Call 020 4511 9511 · WhatsApp 07863 083315
Frequently asked questions
What can I finance?
Providers commonly consider equipment, machinery and vehicles used in the business. For a laundry or launderette, that can include commercial washers, dryers and ironers. Cafe, salon, trade and transport equipment may also be considered. The provider will look at the asset, the supplier and your business.
Can I finance used equipment, or only new?
Used equipment may be considered, depending on its age, condition, value and the supplier. The provider will decide what they are willing to fund. A clear supplier quote helps.
What is the difference between hire purchase and a lease?
With hire purchase, you typically own the asset once you have made the agreed payments and any final option-to-purchase payment. With a finance or operating lease, you are paying to use the asset; you do not automatically own it at the end, and the end-of-term options depend on the agreement. We will explain this before any introduction is made.
How much deposit will I need, and how long is the term?
This varies by provider, by asset and by the strength of the case. Some agreements can be arranged with a low deposit or, in some cases, no deposit; others will need a contribution. Terms are often set over a number of years, commonly two to five, but this is not fixed. We will not quote a rate or a term until a provider has assessed your case.
Is asset finance regulated by the FCA?
It depends on the type of business and the agreement. Finance provided to a limited company for business use is often not regulated by the Financial Conduct Authority. Finance for a sole trader or a small partnership can, in some cases, be regulated consumer credit. We will tell you if an introduction would involve a regulated product, and we will only proceed where we are able to do so. Some business finance is not regulated by the FCA.
Do you charge a fee, and are you paid commission?
We will be clear about any fee before you decide to proceed. We may also receive a commission from the finance provider if an agreement is completed. We will tell you about this. SM Finance does not lend the money; we act as an introducer.
How long does an application take?
Timescales depend on how complete your documents are, how quickly the supplier can confirm the quote, and how long the finance provider takes to assess the case. We will keep you updated. We cannot promise a decision in a set number of days.
What if asset finance is not right for me?
We will say so. You may be better suited to a business loan, or to a commercial or owner-occupier mortgage if the need is for premises rather than equipment. We can discuss those options with you.
Talk to us about asset finance
If you are planning to buy equipment or vehicles for your business — including commercial laundry machinery — we are happy to talk it through.
- Enquire online: smfinance.co.uk/contact-us
- Call: 020 4511 9511
- WhatsApp: 07863 083315
- Email: info@smfinance.co.uk
- Visit or write: 16A Raven Road, London E18 1HB
- Hours: Monday to Saturday, 8.00am to 6.00pm
Important information
SM Finance is a trading style of Selina Manir Finance Limited, which acts as an introducer to 3Q Financial Ltd. 3Q Financial Ltd is authorised and regulated by the Financial Conduct Authority (FRN 930781).
For asset finance and other business finance, Selina Manir Finance Limited acts as an introducer to a panel of finance providers. We do not lend the money ourselves. We may receive a commission from a finance provider if an agreement goes ahead, and we will tell you about this. Finance is subject to status and is for business use only. Some business finance is not regulated by the Financial Conduct Authority.
Your right to use the asset, and whether you will own it at the end of the term, depends on the type of agreement. If any finance is secured on your home or other property, your home or property may be repossessed if you do not keep up repayments.